
Quarterly Key Data Report Q2 2026
1. Background
ComReg collects statistical data from authorised operators on a quarterly basis. Not all such operators are included in this data collection (based on minimum revenue levels), but ComReg aims to represent 95% of the total markets. This data includes information on subscriptions, lines, revenues, broadband speeds, minutes and data usage for both fixed and mobile voice and broadband. The data and charts included below are a subset of the information collected. The detailed presentations of data are available on the ComReg data portal.
Map visualisations for ‘FTTP’ and ‘Gigabit’ Coverage and Take-Up statistics by County, Local Electoral Area, Electoral Division and other Geographic units can be found at ComReg’s Open Data Map Hub.
Data presented in this Summary of the Quarterly Key Data is based on questionnaires completed by certain authorised operators for the period from 1st April 2026 to 30th June 2026. The report is based on submissions from 55 active operators.
Q2 2026 Infographic
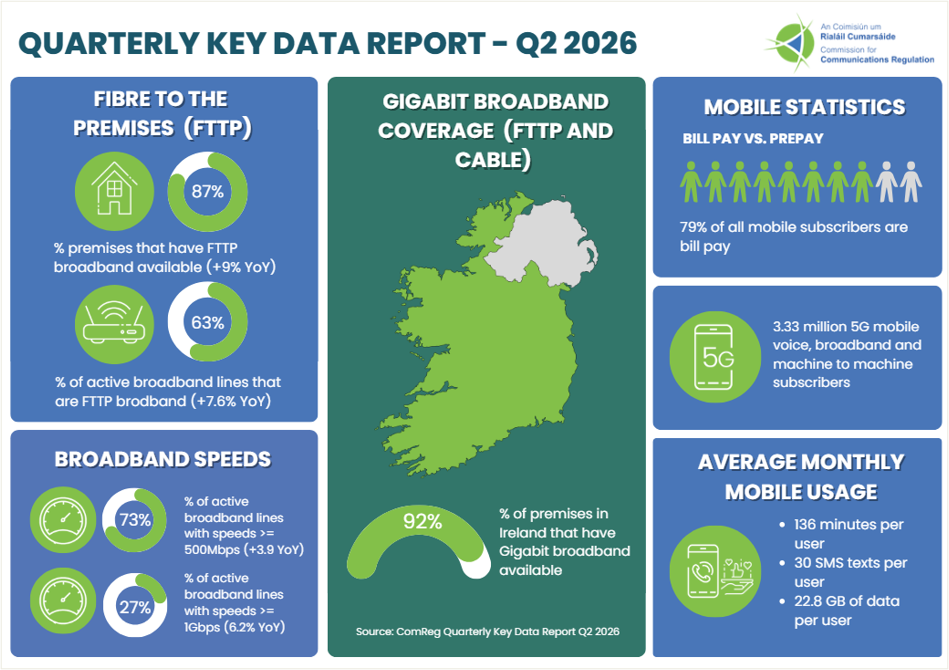
Fibre to the Premises (FTTP)
87% of premises have FTTP broadband available.
63% of active broadband lines are FTTP broadband.
Broadband Speeds
- 73% of active broadband lines have speeds 500 Mbps or greater.
- 27% have speeds of 1 Gbps or greater.
Gigabit Broadband Coverage
92% of premises in Ireland have Gigabit broadband available.
Mobile Statistics
79% of mobile subscribers are on bill pay.
3.33 million 5G mobile, broadband, and machine-to-machine subscribers.
Average Monthly Mobile Usage
- 136 minutes per user
- 30 SMS texts per user
- 23 GB of data per user
2. Overview of Irish Communications Market Q2 2026
Table 1 – Communications Summary
| Summary | 2025 Q2 | 2025 Q3 | 2025 Q4 | 2026 Q1 | 2026 Q2 |
|---|---|---|---|---|---|
| Total Retail Market Revenues (000s) | €921,811 | €922,885 | €949,743 | €914,576 | €938,677 |
| Total Fixed Line Wholesale Revenues (000's) | €151,734 | €155,233 | €161,204 | €156,774 | €159,265 |
| Total Mobile Wholesale revenues (000's) | €30,108 | €32,294 | €31,352 | €29,517 | €30,968 |
| Percentage Premises with FTTP Broadband Available | 78.5% | 81.0% | 84.3% | 85.7% | 87.1% |
| Percentage Premises with Gigabit Broadband (FTTP or Cable) Available | 87.7% | 88.9% | 90.0% | 91.1% | 91.9% |
| FTTP Take Up Rate | 50.2% | 50.6% | 50.7% | 51.9% | 52.5% |
| FTTP & Cable Take Up Rate | 58.4% | 58.9% | 59.7% | 60.5% | 60.8% |
| Total Fixed Broadband Subscriber Lines | 1,716,609 | 1,757,462 | 1,765,075 | 1,775,490 | 1,789,356 |
| Total Fixed Voice (PSTN, ISDN and VOIP) Subscriber Lines | 1,032,148 | 1,009,554 | 995,826 | 989,867 | 972,447 |
| Mobile Subscriptions inc. MBB and M2M - Total | 10,561,301 | 10,732,236 | 10,844,594 | 10,920,348 | 11,028,477 |
| Machine to Machine (M2M) Subscriptions | 4,179,852 | 4,276,911 | 4,367,068 | 4,427,745 | 4,481,995 |
| Mobile Broadband (MBB) Subscriptions | 393,253 | 394,084 | 393,979 | 393,356 | 394,453 |
| Mobile Subscriptions exc. MBB and M2M - Total | 5,988,196 | 6,061,241 | 6,083,547 | 6,099,247 | 6,152,029 |
| Total Voice Traffic Minutes (000s) | 2,943,972 | 2,930,822 | 2,950,700 | 2,845,107 | 2,702,746 |
| Total Fixed Voice Minutes (000s) | 215,632 | 211,880 | 206,315 | 208,705 | 189,791 |
| Total Mobile Voice Minutes (000s) | 2,728,340 | 2,718,942 | 2,744,385 | 2,636,402 | 2,512,955 |
Fixed Market
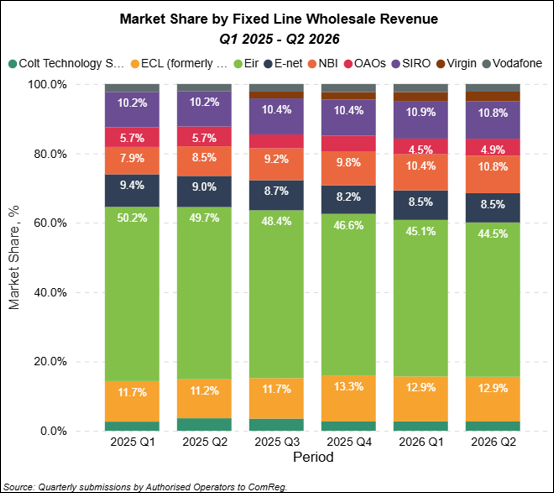
- In Q2 2026, Eir had the highest wholesale revenue share in the fixed line market at 44.5%.
- ComReg estimates that the next seven largest operators (ECL (formerly BT), NBI, SIRO, Virgin Media Ireland, Vodafone, E-Net and Colt Technologies) contribute a further 50.6% share of fixed line retail market revenue.
- Remaining other authorised operators (OAOs) account for the residual 4.9% share.
Figure 1 – Fixed Line Market Shares (Wholesale Revenue) Q1 2025 – Q2 2026
Retail Fixed Voice Market
- Fixed voice traffic in Q2 2026 was approximately 190 million minutes, which was a 9.1% increase on Q1 2026 and a decrease of 12% since Q2 2025.
- At the end of Q2 2026, there were 972,447 fixed voice subscriber lines, a decrease of 1.8% since Q1 2026 and a decrease of 5.8% since Q2 2025.
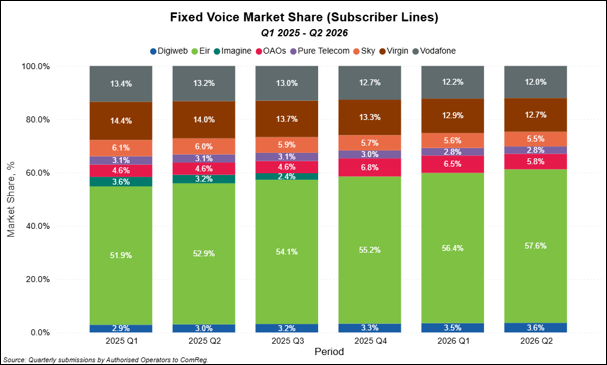
- As of Q2 2026, Eir had 57.6% of all fixed voice subscriber lines followed by Virgin Media (12.7%), Vodafone (12.0%), Sky Ireland (5.5%), Digiweb (3.6%), and Pure Telecom (2.8%). Other operators accounted for the remaining 5.8% of fixed voice subscriber lines.
Figure 2 – Retail Fixed Voice Subscriber Lines
3. Retail Broadband Market
- At the end of June 2026, there were almost 2.18 million active total Broadband subscriber lines in Ireland.
- This is a 0.5% increase from the previous quarter and a 3.5% increase on Q2 2025.
- Looking at total Fixed Broadband lines only, these increased by 0.5% since Q1 2026, with a 4.2% annual increase on Q2 2025.
Table 2 – Total Number of Active Broadband Subscriber Lines
| Line Type | Q2 2026 | Quarterly Change Q1'25 – Q2'26 | Annual Change Q2'25 - Q2'26 |
|---|---|---|---|
| Cable Broadband | 264,079 | -3.7% | -12.2% |
| DSL Broadband | 36,624 | -7.3% | -26.7% |
| VDSL Broadband | 246,457 | -6.6% | -22.5% |
| FTTP Broadband | 1,133,964 | 3.7% | 18.4% |
| Satellite Broadband | 38,181 | 16.7% | 92.1% |
| FWA Broadband | 70,051 | -7.4% | 0.1% |
| Total Fixed Broadband | 1,789,356 | 0.5% | 4.2% |
| Mobile Broadband | 394,453 | 0.28% | 0.31% |
| Total Broadband | 2,183,809 | 0.49% | 3.50% |
- FTTP (+3.7%), Satellite (+16.7%) and Mobile Broadband (0.28%) subscriber lines showed positive growth this quarter.
- VDSL (-6.6%), DSL (-7.3%), Cable (-3.7%), FWA (-7.4%) subscriber lines fell this quarter.
Figure 3 – Retail Fixed Broadband Market Shares based on Subscriber Lines
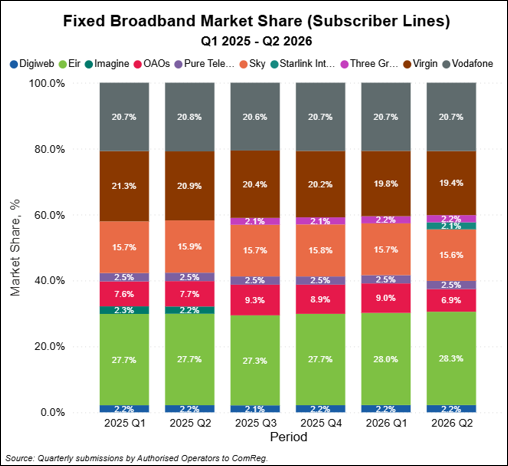
- In Q2 2026, Eir had 28.3% of total retail fixed broadband subscriber lines, followed by Vodafone at 20.7%, Virgin Media at 19.4%, Sky Ireland at 15.6%, Pure Telecom at 2.5%, Three Group at 2.2% and Starlink at 2.1%.
- All other authorised operators (OAOs) combined accounted for the remaining 6.9% share of retail fixed broadband subscriber lines.
Table 3 – Retail Fixed Broadband Subscriber Lines by Sold Download Speed
| Fixed Broadband Subscriber Lines by Sold Speed | Q1 2026 | Q2 2026 | Quarterly Change |
|---|---|---|---|
| <2Mbps - 9.99Mbps | 1.50% | 1.38% | -0.11% |
| 10Mbps - 29.99Mbps | 2.36% | 2.18% | -0.17% |
| 30Mbps - 99.99Mbps | 14.91% | 13.84% | -1.03% |
| 100Mbps - 499.99Mbps | 9.11% | 9.82% | 0.49% |
| 500Mbps - 999.99Mbps | 46.25% | 45.45% | -0.69% |
| >=1GB - 1.99GB | 24.25% | 25.45% | 1.25% |
| >=2GB - 4.99GB | 0.61% | 0.66% | 0.05% |
| >=5GB - 10GB | 1.00% | 1.21% | 0.21% |
- In Q2 2026, 82.6% of all fixed broadband subscriber lines had sold download speeds which were equal to or greater than 100Mbps, with 72.8% having sold download speeds equal to or greater than 500Mbps.
- Those having sold download speeds equal to or greater than 1GB increased by 2.0 percentage points quarter on quarter and stood at 27.3%.
Figure 4 – FTTP Subscriber Line Market Share
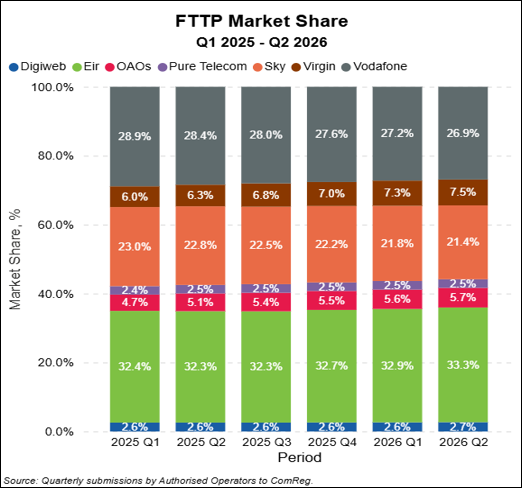
- In Q2 2026, Eir had 33.3% of retail Fibre to the Premises (FTTP) subscriber lines, followed by Vodafone at 26.9%, Sky Ireland at 21.4%, Virgin Media at 7.5%, Digiweb at 2.7% and Pure Telecom at 2.5%.
- Other operators accounted for the remaining 5.7%.
4. Broadband Market – Networks
Figure 5 – Network FTTP Active Subscriber Lines by Quarter
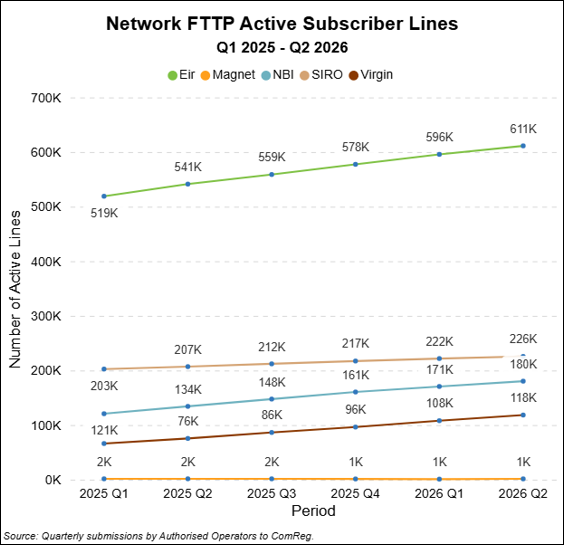
- In Q2 2026, based on the underlying network, 611k (up 2.6% QoQ) of the active FTTP subscriber lines were sold on the Eir network
- 226k (up 1.7% QoQ) were on the Siro network
- 180k (up 5.7% QoQ) were on the NBI network
- 118k (up 9.6% QoQ) were on the Virgin Media network
- 1k were on the Magnet Network.
Figure 6 – Network FTTP Broadband Rollout (No. of Lines) by Quarter
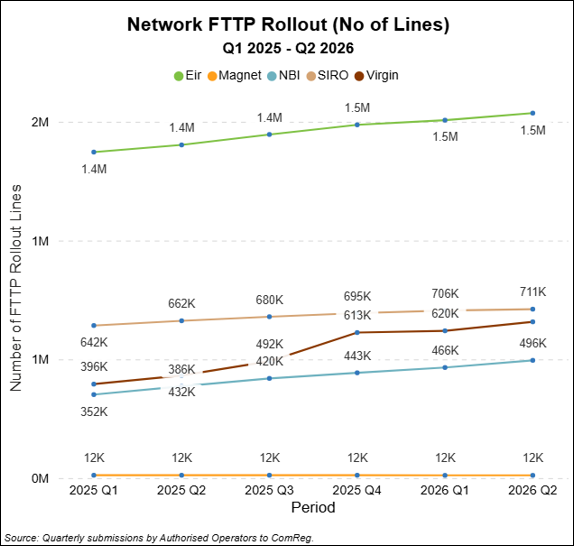
- In Q2 2026, Eir reported having rolled out 1.54m (up 2% QoQ) FTTP broadband lines, followed by Siro with 711k (up 0.8% QoQ), Virgin Media Ireland with 658k (up 6.1% QoQ), NBI with 496k (up 6.5% QoQ), with Magnet having rolled out 11.7k lines and Crossan 63 lines.
Total Gigabit (FTTP and Cable) Coverage
- Map visualisations for Gigabit Coverage and Take-Up statistics by County, Local Electoral Area, Electoral Division and other geographic units can be found at ComReg’s Open Data Map Hub
- 87.1% (up 1.4 percentage points QoQ) of all premises (as measured by Eircodes) in Ireland had FTTP broadband available at the end of Q2 2026.
- 91.9% (up 0.8 percentage points QoQ) of all premises (as measured by Eircodes) in Ireland had Gigabit broadband available at the end of Q2 2026.
- The county with the highest level of FTTP coverage is Westmeath at 95%. Westmeath and Longford have the highest level of Gigabit coverage at 96%. Every county had a minimum of 80% FTTP coverage at the end of Q2.
- Dublin has the fastest growing FTTP coverage within the last year, with a 15-percentage point annual increase in FTTP coverage to now stand at 80% coverage.
- Mayo shows the highest quarter‑on‑quarter increase in FTTP coverage, rising by 6.5-percentage points compared with the previous quarter.
- ComReg’s Open Data Map Hub includes additional geographic units including Local Electoral Area, Electoral Division and Small Area
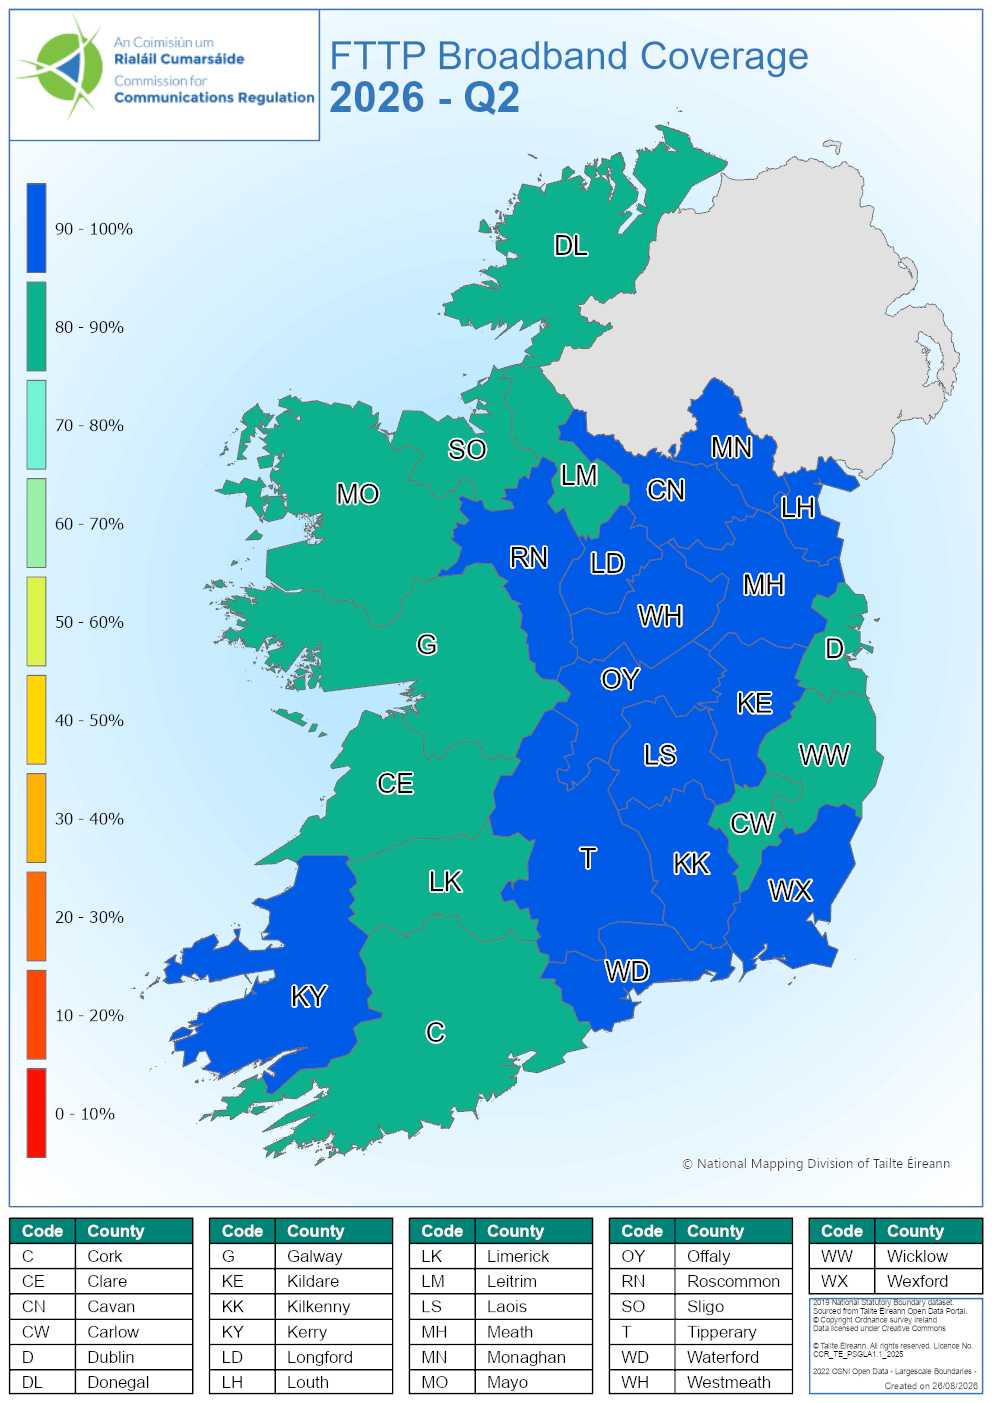
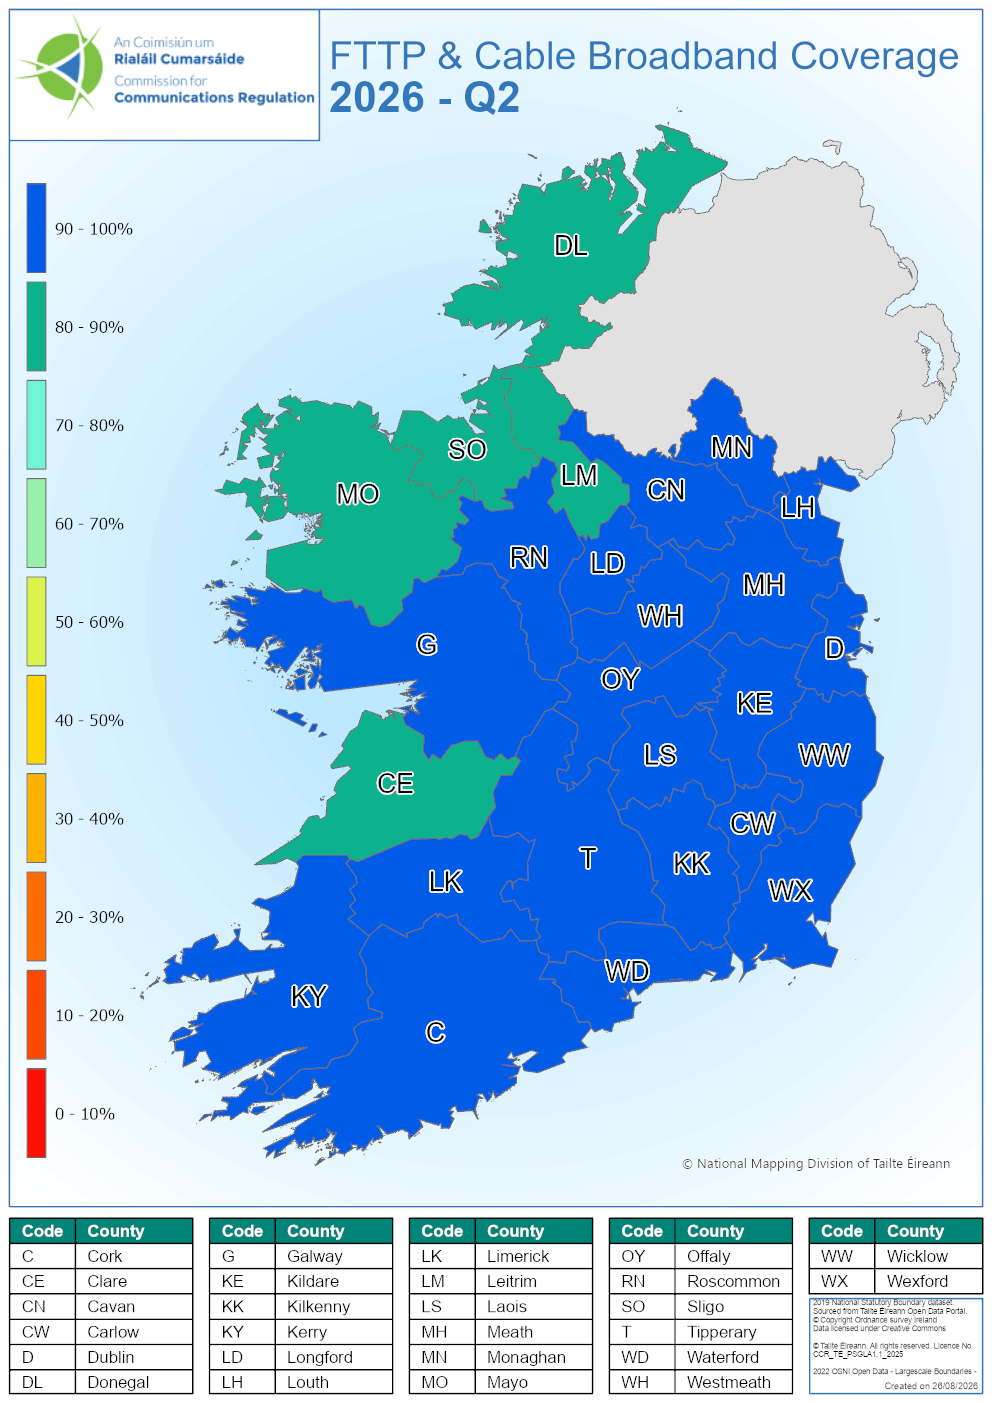
Total Gigabit (FTTP and Cable) Coverage
- In terms of FTTP take-up (active FTTP broadband premises divided by premises where FTTP is available), 52.5% of all premises (up 2 percentage points YoY) with FTTP broadband available had an active FTTP service at the end of Q2 2026.
- 60.8% of premises with FTTP or Cable available had an active FTTP or Cable service at the end of Q2 2026.
- The maps set out below show County level ‘FTTP’ and ‘Gigabit’ take-up rate by County for Q2 2026.
- The county with the highest level of FTTP take-up is Meath at 67%. Longford had the fastest growing FTTP take-up rate within the last year, with a 6.5-percentage point increase in take-up compared to Q2 2025.
- See ComReg’s Open Data Map Hub for further map visualisations on Gigabit broadband.
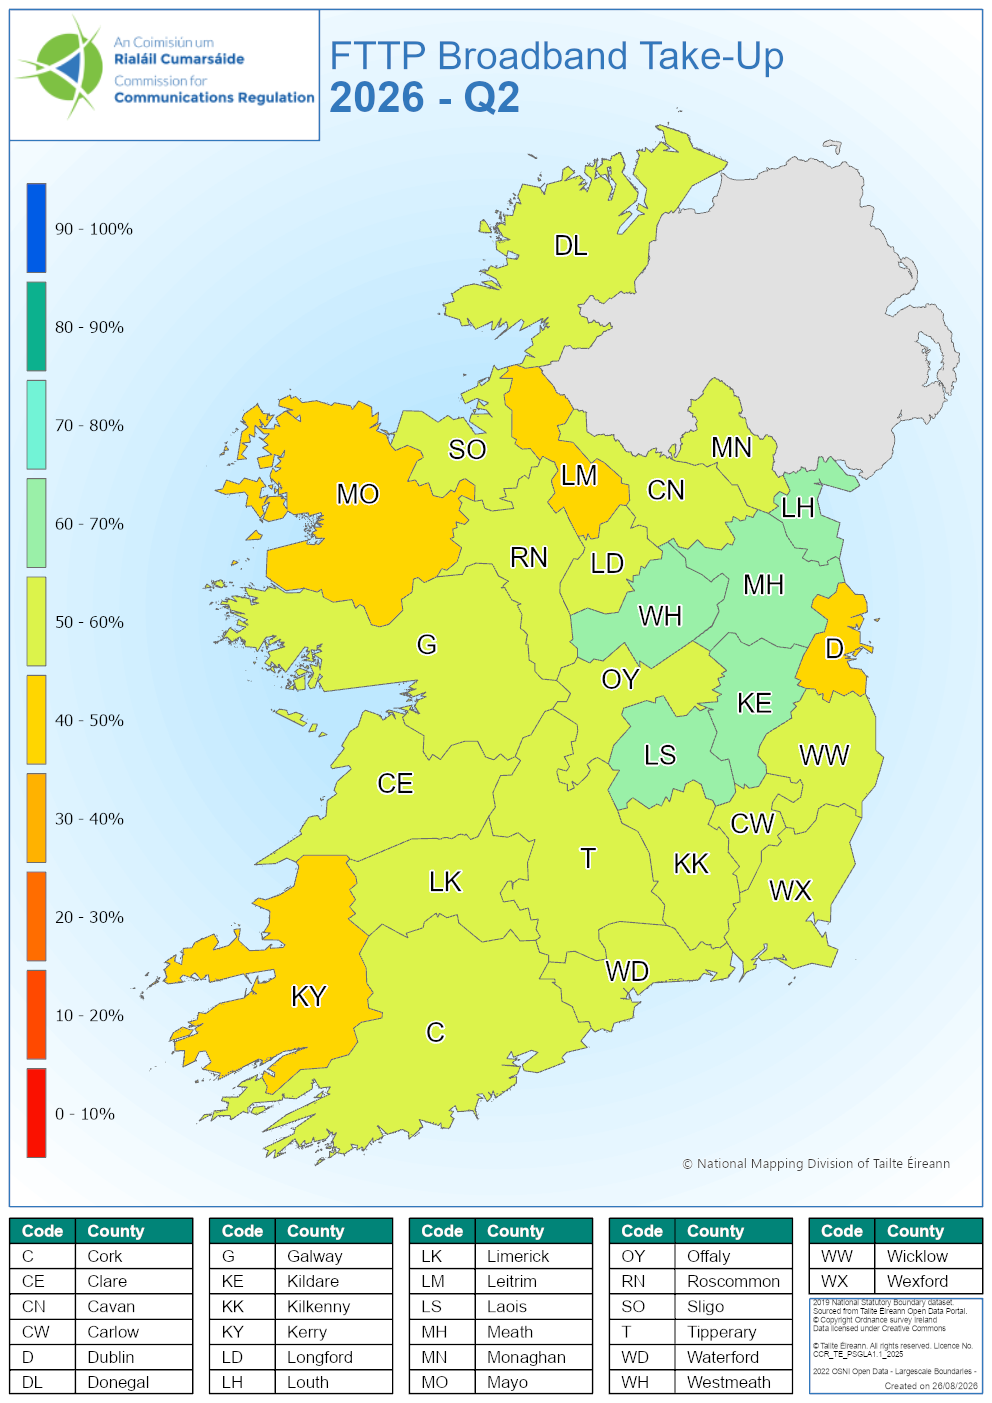
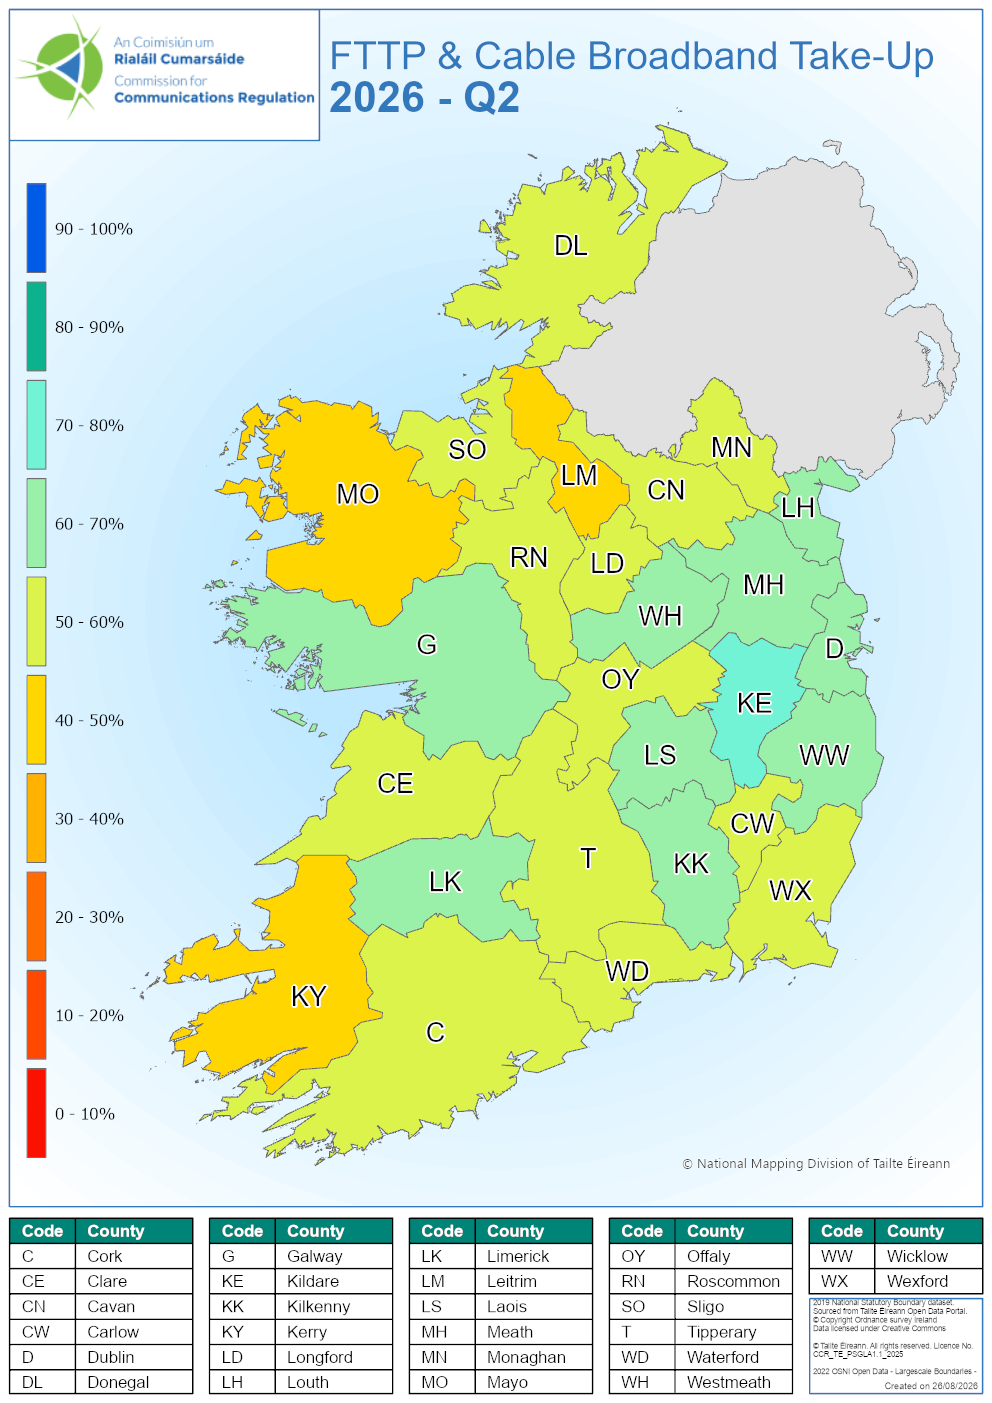
Total Gigabit (FTTP and Cable) Take-Up
- In terms of FTTP take-up (active FTTP broadband premises divided by premises where FTTP is available), 51.9% of all premises (up 2 percentage points YoY) with FTTP broadband available had an active FTTP service at the end of Q1 2026.
- 60.5% of premises with FTTP or Cable available had an active FTTP or Cable service at the end of Q1 2026.
- The maps set out below show County level ‘FTTP’ and ‘Gigabit’ take-up rate by County for Q1 2026.
- The county with the highest level of FTTP take-up is Meath at 65%. Longford had the fastest growing FTTP take-up rate within the last year, with a 6.5-percentage point increase in take-up compared to Q1 2025.
- See ComReg’s Open Data Map Hub for further map visualisations on Gigabit broadband.
5. Mobile Market
At the end of Q2 2026 there were 11,028,477 mobile subscriptions in Ireland, including mobile broadband (MBB) and Machine to Machine (M2M). If mobile broadband subscriptions (394,453) and M2M subscriptions (4,481,995) are excluded, the total number of mobile voice subscriptions was 6,152,029.
Figure 7 – Market Shares by Subscription including Mobile Broadband and Machine to Machine
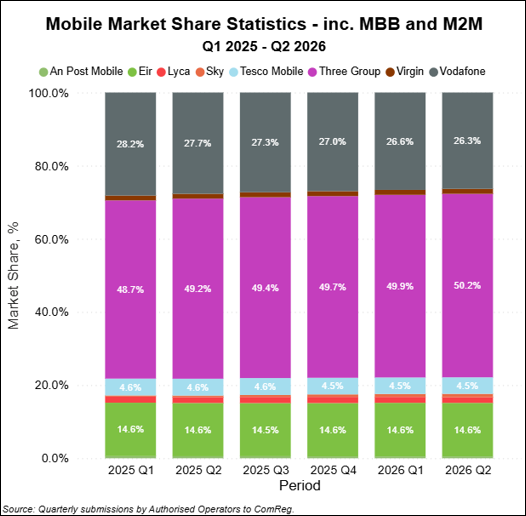
In Q2 2026 Three had the largest share of mobile subscriptions including MBB and M2M at 50.2%. This was followed by Vodafone with 26.3%, Eir with 14.6%, Tesco Mobile at 4.5%, Lyca Mobile at 1.5%, Virgin Mobile at 1.4%, Sky Mobile at 0.9% and An Post Mobile at 0.5%.
Figure 8 – Market Shares by Subscription excluding Mobile Broadband and Machine to Machine
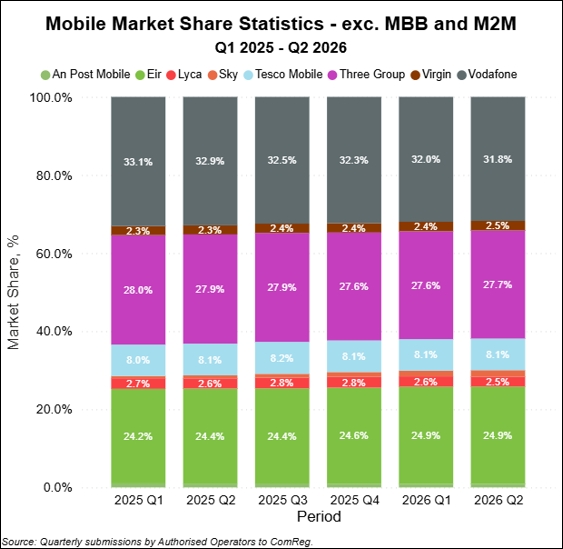
In Q2 2026 Vodafone had the highest market share excluding mobile broadband and M2M (31.8%), followed by Three (27.7%), Eir (24.9%), Tesco Mobile (8.1%), Lyca (2.5%), Virgin Mobile (2.5%), Sky Mobile (1.7%) and An Post Mobile (0.9%).
Figure 9 – Mobile Subscriptions by Technology
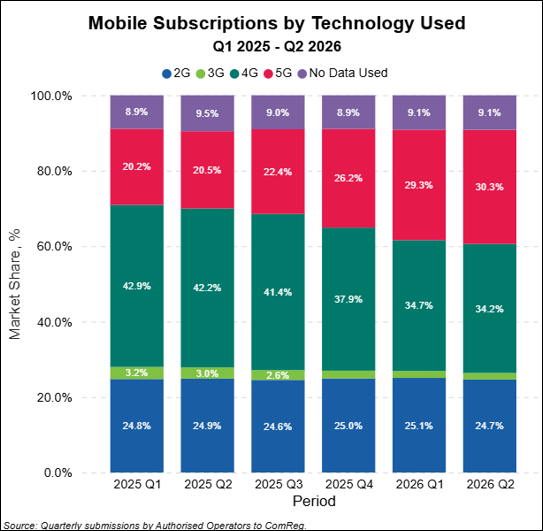
There were 2,719,485 2G (24.7%), 190,332 3G (1.7%), 3,773,093 4G (30.3%) and 3,337,063 5G (30.3%) mobile subscriptions in Q2 2026. 1,008,504 (9.1%) mobile subscriptions did not record any use of data in Q2
6. Revisions
Note 1: Starlink revised satellite broadband subscribers for Q1 2026.
Note 2: Sky Data Traffic for Q2 2026 was estimated.
Note 3: Tetra revised revenues for Q1 2026.
Note 4: Ivertec revised VOIP subscriber numbers for Q4 2025 and Q1 2026.
Note 5: Ivertec revised revenues for Q1 2026.
Note 6: Three revised revenues for Q1 2026.
Note 7: Aptus revised VOIP and Double Play bundles for Q1 2025 – Q4 2025.
7. Appendix 1: Legal Disclaimer
The information and statistics contained within this document are derived from a variety of sources, but it is mostly reliant on data obtained from authorised operators.
This document does not constitute commercial or other advice. No warranty, representation or undertaking of any kind, express or implied, is given in relation to the information and statistics contained within this document.
To the fullest extent permitted by law, neither the Commission for Communications Regulation (“ComReg”) nor any of its employees, servants or agents will be liable for any loss or damage arising out of or in connection with your use of, or any reliance whatsoever placed on this document (including, but not limited to, indirect or consequential loss or damages, loss of income, profit or opportunity, loss of or damage to property and claims of third parties) even if ComReg has been advised of the possibility of such loss or damages or such loss or damages were reasonably foreseeable.